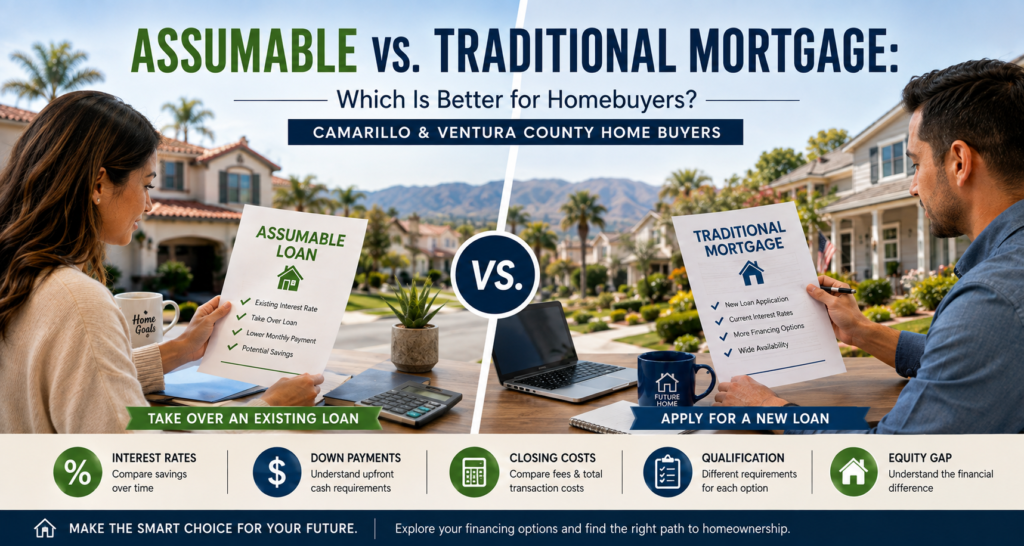
A split-screen image showing two paths to homeownership. On one side, a buyer reviews an existing mortgage labeled “Assumable Loan.” On the other, a buyer reviews a new mortgage application labeled “Traditional Mortgage.” Use a bright Southern California home or Camarillo neighborhood as the background.
Assumable vs. Traditional Mortgage: Which Is Better for Homebuyers?
When you’re buying a home in Camarillo or elsewhere in Ventura County, choosing the right property is only one part of the decision. Choosing the right financing can have a major impact on your monthly payment, upfront costs, and long-term budget.
Most homebuyers are familiar with a traditional mortgage, where they apply for a brand-new loan based on current interest rates and lending requirements. But another option may be available on certain properties: an assumable mortgage.
An assumable mortgage allows a qualified buyer to take over the seller’s existing mortgage rather than applying for an entirely new one.
So, which option is better?
The answer depends on the interest rate attached to the existing loan, how much equity the seller has, your available funds, and your financial qualifications. Here’s how assumable and traditional mortgages compare.
What Is the Difference Between an Assumable and Traditional Mortgage?
Assumable Mortgage
With an assumable mortgage, the buyer takes over the seller’s existing loan, including the remaining balance, interest rate, and remaining repayment term, subject to the loan servicer’s approval and program rules.
Assumable loans are most commonly associated with certain government-backed mortgages, such as:
- FHA loans
- VA loans
- USDA loans
Not every mortgage can be assumed, so buyers should always verify the loan type and assumption requirements.
Traditional Mortgage
A traditional mortgage involves applying for a new home loan from a lender.
The buyer’s new mortgage is based on factors such as:
- Current interest rates
- Credit profile
- Income and employment
- Debt-to-income ratio
- Down payment
- Loan program requirements
For many buyers purchasing Ventura County homes, a traditional mortgage is the most familiar and widely available financing option.
Let’s take a closer look at each factor.
1. Comparing Interest Rates
Interest rates are often the biggest reason buyers become interested in assumable loans.
Imagine a homeowner purchased a property several years ago and secured a mortgage with a significantly lower interest rate than what is available when you are buying.
If that mortgage is assumable, a qualified buyer may be able to take over that lower rate.
For example, imagine:
- Seller’s existing mortgage rate: 3.25%
- Current rates available to a buyer: Higher than the seller’s rate
Assuming the seller’s mortgage could potentially result in a lower monthly principal and interest payment compared with taking out a completely new loan for the remaining balance.
The Advantage of an Assumable Loan
A lower existing interest rate can make a significant difference over time, particularly in higher-priced areas of the Southern California housing market.
The Advantage of a Traditional Mortgage
A traditional mortgage allows buyers to finance the full amount they qualify for based on the purchase price and their down payment. You are not limited to homes that happen to have an eligible assumable mortgage.
Bottom line: If the seller’s existing rate is substantially lower than current rates, an assumable mortgage may offer a meaningful advantage.
2. Down Payment and Upfront Cash
This is where the comparison can become more complicated.
With a traditional mortgage, your down payment is generally based on the purchase price and the requirements of your chosen loan program.
Depending on the loan type and your qualifications, buyers may have access to different down payment options.
With an assumable mortgage, however, you need to consider the seller’s existing equity.
Understanding the Equity Gap
Let’s say a Ventura County home is selling for $800,000.
The seller still owes $500,000 on their mortgage.
The difference is:
$800,000 purchase price – $500,000 remaining loan balance = $300,000 equity gap
The buyer generally needs to cover that $300,000 difference through available funds, approved secondary financing, or another acceptable financing arrangement.
This means an assumable loan with an attractive interest rate could still require a larger amount of upfront cash.
Which Option Is Better?
- Buyers with substantial savings or another financing solution may find an assumable loan attractive.
- Buyers with limited upfront funds may find a traditional mortgage easier to structure.
The best option depends on both your available cash and the terms of the financing.
3. Closing Costs
Closing costs are another important part of buying a home in Camarillo or Ventura County.
With a traditional mortgage, buyers typically encounter costs related to:
- Loan origination and lender fees
- Appraisal
- Title and escrow services
- Prepaid taxes and insurance
- Government or recording fees
- Other transaction-related expenses
An assumable mortgage may have a different fee structure because the buyer is taking over an existing loan rather than originating an entirely new one.
However, buyers should not assume that closing costs will automatically be lower.
There may still be:
- Assumption or processing fees
- Title and escrow costs
- Recording fees
- Prepaid expenses
- Costs related to secondary financing, if needed
The Important Takeaway
Always review the estimated costs for both options before deciding. A lower interest rate does not automatically mean the assumable loan will have lower total upfront costs.
4. Qualification Requirements
Both assumable and traditional mortgages require buyers to meet financial qualifications.
Qualifying for an Assumable Mortgage
The buyer typically needs to go through an approval process with the loan servicer or lender.
Requirements may include:
- Credit review
- Income verification
- Debt-to-income review
- Asset documentation
- Program-specific eligibility requirements
The exact process depends on the type of mortgage being assumed.
For VA loans, additional considerations may apply, including eligibility rules and potential impacts on the seller’s VA loan entitlement.
Qualifying for a Traditional Mortgage
With a traditional mortgage, buyers apply for a completely new loan.
The lender evaluates factors such as:
- Credit history
- Income
- Employment
- Existing debt
- Assets
- Down payment
- Property type
Traditional mortgages also give buyers more flexibility because they can choose from multiple loan programs and lenders.
Which Is Easier to Qualify For?
Neither option is automatically easier.
An assumable mortgage may have an attractive existing interest rate, but the buyer still needs to meet the applicable approval requirements.
A traditional mortgage may provide more options, especially if buyers need a loan structure tailored to their financial situation.
5. Equity Requirements: One of the Biggest Differences
Seller equity is one of the most important factors when comparing an assumable mortgage with a traditional mortgage.
If a seller has owned their home for several years, they may have built substantial equity through:
- Mortgage payments
- Home appreciation
- Improvements that increased the property’s value
The more equity a seller has, the larger the potential gap between the remaining mortgage balance and the home’s purchase price.
Why Equity Matters
Suppose a Camarillo home is selling for $900,000, but the seller only owes $400,000 on their assumable mortgage.
The buyer would need to account for the $500,000 difference.
That can be challenging for buyers who do not have significant available cash or access to approved additional financing.
With a traditional mortgage, the buyer instead finances a new loan based on the home’s purchase price, minus the required down payment.
This is often a simpler structure for buyers who want to minimize the amount of cash needed upfront.
When an Assumable Mortgage May Make Sense
An assumable mortgage could be worth exploring if:
- The existing interest rate is significantly lower than current market rates.
- The seller’s remaining loan balance is substantial enough to make the assumption worthwhile.
- You have funds available to cover the seller’s equity.
- You qualify under the loan’s assumption requirements.
- The overall numbers make financial sense after comparing all costs.
For the right buyer, an assumable mortgage can be a valuable opportunity when buying a home in Camarillo or elsewhere in Ventura County.
When a Traditional Mortgage May Be the Better Choice
A traditional mortgage may be a better fit if:
- You need more financing flexibility.
- You have a limited amount available for upfront costs.
- The seller’s home has substantial equity.
- The existing mortgage rate does not offer enough of an advantage.
- You want to compare multiple lenders and loan programs.
- You are not able to meet the requirements for assuming the existing loan.
Traditional financing remains the most common path for buying a home and gives buyers access to a wider selection of properties.
How Should Camarillo and Ventura County Buyers Compare Their Options?
The best approach is to look beyond the interest rate.
Before deciding between an assumable and traditional mortgage, compare:
1. Monthly Payment
Calculate the estimated payment under both financing options.
2. Upfront Cash Needed
Consider the down payment, seller equity gap, closing costs, reserves, and other expenses.
3. Total Financing Costs
A lower interest rate can be valuable, but buyers should also consider fees, loan balances, and how long they plan to own the home.
4. Qualification Requirements
Make sure you understand what the lender or loan servicer requires before moving forward.
5. Your Long-Term Plans
Your ideal financing strategy may depend on whether you plan to stay in the home for a few years or for the long term.
Assumable vs. Traditional Mortgage: Which Is Better?
There is no one-size-fits-all answer.
An assumable mortgage can be an excellent opportunity for buyers who can qualify and benefit from an existing lower interest rate. However, the seller’s equity can create a significant upfront financial requirement.
A traditional mortgage may come with current market interest rates, but it often provides more flexibility in loan programs, lenders, down payment options, and property selection.
For buyers exploring Camarillo real estate or Ventura County homes, the best choice comes down to the complete financial picture, not just the advertised interest rate.
Before making a decision, consider speaking with a qualified mortgage professional who can review your financial situation and explain the available financing options.
Final Thoughts
Buying a home in today’s Southern California housing market means looking at more than just the listing price. Financing can play a major role in determining what a home will cost you each month and how much cash you need to purchase it.
Assumable loans can offer an interesting alternative to traditional financing, particularly when a property has an existing mortgage with a favorable interest rate. At the same time, traditional mortgages continue to offer flexibility and may be a better fit for many buyers.
The key is understanding the numbers before making an offer.
If you’re interested in buying a home in Camarillo, Ventura County, or surrounding Southern California communities, it’s helpful to explore all of your available options and understand how each financing strategy could affect your homebuying goals.