One of the biggest questions first-time homebuyers ask is: How much money do I actually need to buy a home?
Many people assume they need to save only for a down payment. While the down payment is an important part of buying a home, it is not the only expense buyers should prepare for.
When buying a home in Camarillo, Ventura County, or another Southern California community, it is important to understand the full financial picture before you begin your home search.
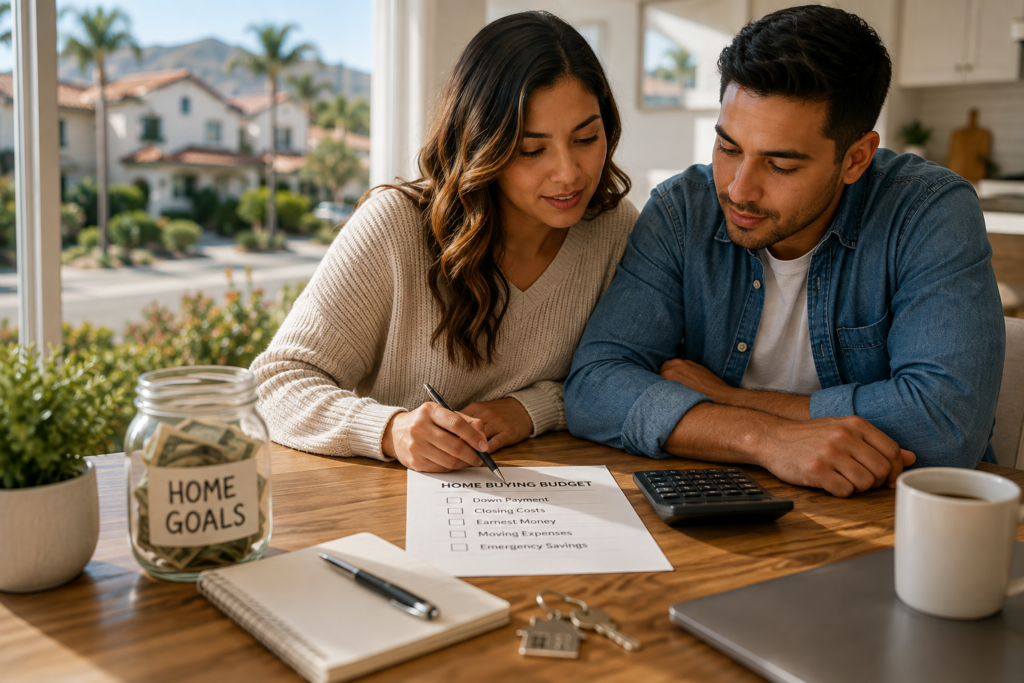
In addition to your down payment, you may need to budget for closing costs, an earnest money deposit, moving expenses, and emergency savings after you receive the keys.
The good news is that you do not necessarily need to have every dollar saved before you start learning about your options. Different loan programs, assistance programs, and financing options may be available depending on your situation.
Here are five important expenses first-time homebuyers should understand.
1. Your Down Payment
The down payment is usually the first expense buyers think about when purchasing a home.
Your down payment is the portion of the home’s purchase price that you pay upfront. The remaining amount may be financed through a mortgage.
However, the common belief that every buyer needs a 20% down payment is not always true.
Depending on the loan program and your qualifications, buyers may have access to financing options with different down payment requirements.
For example, some buyers may qualify for:
- Conventional loans with lower down payment options
- FHA loans
- VA loans for eligible borrowers
- USDA loans in eligible areas
- Down payment assistance programs, when available and qualified for
Example:
If you are buying a $700,000 home, the amount needed for your down payment will depend on your loan program and financing terms.
A 20% down payment would be $140,000, but some loan programs may allow qualified buyers to purchase with a lower percentage.
That is why it is important to speak with a qualified mortgage professional before assuming that a particular down payment amount is required.
The Key Takeaway
Instead of asking, “Do I have 20% saved?” consider asking:
“What loan programs may be available to me, and how much would I realistically need for my down payment?”
2. Closing Costs
Closing costs are another important expense that first-time homebuyers should include in their budget.
These are the costs associated with completing the home purchase and finalizing the transaction.
Depending on the property, loan, and transaction details, closing costs may include expenses related to:
- The mortgage loan
- The appraisal
- Title and escrow services
- Recording and government fees
- Prepaid property taxes
- Homeowners insurance
- Other lender or transaction-related costs
The exact amount can vary depending on several factors.
Can Closing Costs Be Reduced?
In some situations, buyers may be able to negotiate for seller concessions, depending on the transaction and market conditions. Some loan programs may also have guidelines regarding how certain costs can be paid.
However, seller concessions are never guaranteed.
Your lender and real estate professional can help you understand what costs to expect and whether there may be opportunities to structure the transaction differently.
3. Earnest Money Deposit
Another cost buyers should understand is the earnest money deposit, sometimes referred to as an EMD.
Earnest money is a deposit submitted after a buyer and seller enter into a purchase agreement. It demonstrates that the buyer is moving forward with the purchase in good faith.
The amount can vary depending on the purchase price, local market practices, and the terms negotiated in the contract.
For first-time homebuyers, it is important to remember that earnest money is generally not an additional fee on top of the home’s purchase price.
Depending on the terms of the transaction, the earnest money deposit is typically credited toward the buyer’s funds needed to close.
However, what happens to the earnest money if the transaction does not close can depend on the terms of the purchase agreement and applicable contingencies.
Before Making an Offer
Make sure you understand:
- How much earnest money is required
- When the deposit is due
- Where the funds will be held
- How the deposit may be applied at closing
- The conditions that could affect the return or release of the funds
Your real estate professional can help you understand the purchase contract, while legal or financial questions should be directed to the appropriate qualified professional.
4. Moving Expenses
Moving costs can be easy to overlook when you’re focused on saving for the home itself.
But once you close on your Ventura County home, you may have several immediate expenses to consider.
These can include:
- Hiring movers
- Renting a moving truck
- Packing supplies
- Storage fees
- Utility deposits or connection costs
- New furniture
- Appliances
- Window coverings
- Minor repairs or updates
- Cleaning supplies and household essentials
The amount can vary widely depending on whether you’re moving locally, relocating from another city, or moving from out of state.
Create a Separate Moving Budget
One helpful strategy is to create a separate budget for your move rather than using all of your savings for your down payment and closing costs.
Even a carefully planned move can come with unexpected expenses.
Having a separate amount set aside for moving can help reduce financial stress during your first few weeks of homeownership.
5. Emergency Savings After You Buy
Buying a home should not mean draining every dollar in your savings account.
Unexpected expenses can happen shortly after moving in.
For example, you may discover that you need to:
- Repair an appliance
- Replace a water heater
- Fix a plumbing issue
- Handle an unexpected home repair
- Replace furniture or essential household items
- Cover a temporary change in income or other personal expenses
This is why emergency savings are an important part of preparing for homeownership.
The amount you should keep in savings depends on your overall financial situation, monthly expenses, job stability, home condition, and other personal factors.
A mortgage professional or financial advisor can help you evaluate your financial readiness.
Remember: The Goal Isn’t to Empty Your Savings
It can be tempting to put every available dollar toward buying your first home, especially in a competitive Southern California housing market.
But leaving yourself with no financial cushion can make homeownership more stressful.
When planning your homebuying budget, consider how much you will have left after:
- Your down payment
- Closing costs
- Earnest money
- Moving expenses
- Immediate home needs
How Much Should You Save Before Buying a Home?
There is no single number that works for every first-time homebuyer.
The amount you need will depend on:
- The price of the home
- Your loan program
- Your down payment requirement
- Your closing costs
- The earnest money required for your offer
- Whether you qualify for assistance programs
- Your moving plans
- Your current savings and monthly expenses
- The amount of emergency savings you want to maintain
A good starting point is to create a complete homebuying budget instead of focusing only on the down payment.
Your First-Time Homebuyer Budget Checklist
Before making an offer on a home, consider budgeting for:
- Down payment
- Closing costs
- Earnest money deposit
- Moving expenses
- Immediate repairs or purchases
- Emergency savings
Looking at all of these expenses together can give you a much clearer picture of what you may need.
A Simple Example for First-Time Buyers
Imagine you are planning to buy a home in Camarillo or another Ventura County community.
Instead of setting a savings goal based only on the home’s down payment, you could organize your budget into categories:
Home Purchase Funds
- Down payment
- Closing costs
- Earnest money deposit
Moving Funds
- Movers or truck rental
- Packing supplies
- Utility setup
- Furniture or household essentials
Financial Safety Net
- Emergency savings
- Unexpected repairs
- Personal living expenses
This approach can help you avoid overlooking costs that may arise before or shortly after closing.
The exact amount you need will depend on your individual situation and financing options.
Tips for First-Time Homebuyers Preparing to Buy
If buying a home feels financially overwhelming, start by taking the process one step at a time.
1. Review Your Current Savings
Understand how much you currently have available and how much you want to keep untouched for emergencies.
2. Talk to a Mortgage Professional Early
You do not need to wait until you find your dream home.
Speaking with a qualified lender can help you understand potential loan options, estimated down payment requirements, and expected closing costs.
3. Avoid Draining Your Savings
Buying a home is a major milestone, but it is important to think about your financial stability after closing.
4. Research Assistance Programs
Depending on your circumstances, there may be local, state, or program-specific assistance options available. Eligibility requirements can vary.
5. Create a Realistic Monthly Budget
Remember to consider the ongoing costs of homeownership, including:
- Mortgage payments
- Property taxes
- Homeowners insurance
- Utilities
- Maintenance and repairs
- HOA fees, if applicable
Understanding these expenses can help you determine what homeownership may realistically look like for your budget.
Buying a Home Is More Than Saving for a Down Payment
For first-time homebuyers, understanding the full cost of buying a home can make the process feel much more manageable.
The goal is not simply to save as much money as possible. It is to understand where your money may go and create a plan that fits your financial situation.
When buying a home in Camarillo, Ventura County, or another Southern California community, preparation can help you move forward with more confidence.
A down payment is only one piece of the puzzle. By planning for closing costs, earnest money, moving expenses, and emergency savings, you can create a more realistic path toward homeownership.
Final Thoughts
Buying your first home is exciting, but it is also a significant financial decision.
Before you begin touring Ventura County homes, take the time to understand your complete homebuying budget. Knowing what expenses to expect can help you avoid surprises and prepare for the transition into homeownership.
You do not need to figure everything out on your own. The right real estate and mortgage professionals can help you understand the process, explore your options, and create a clearer picture of what may be possible for your goals.